IAQF Industry Day
ABOUT THE EVENT
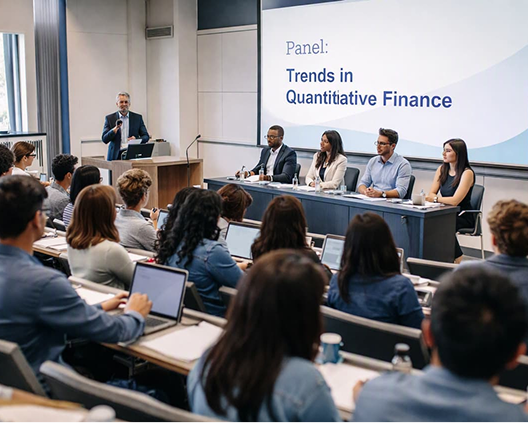
IAQF Industry Day is open to both first- and second-year quantitative finance and financial engineering Master’s students. The event includes industry talks by professionals across key areas of quantitative finance, including risk, quant research, quant trading, developer teams, AI/ML, and startup innovation.
In a rapidly changing job market, our goal is to help students better understand the industry and current hiring trends, narrow down suitable roles and target companies, practice answering brain teaser interview questions, and connect with other quantitative finance professionals.
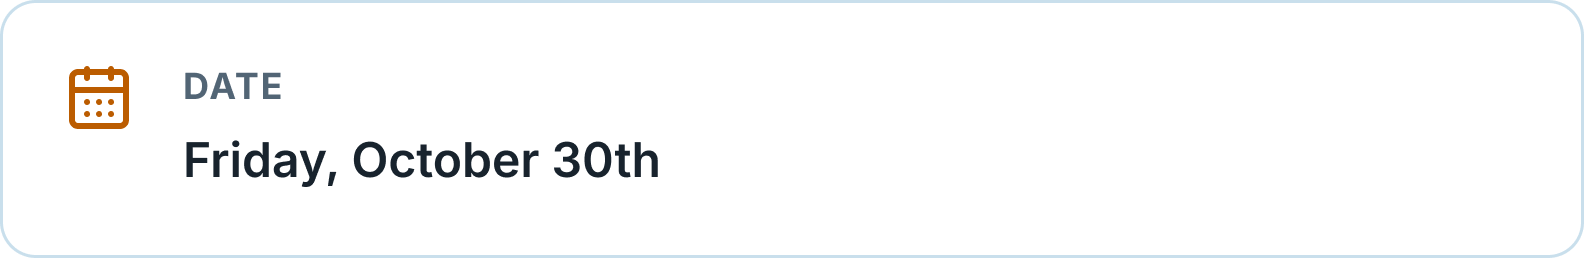
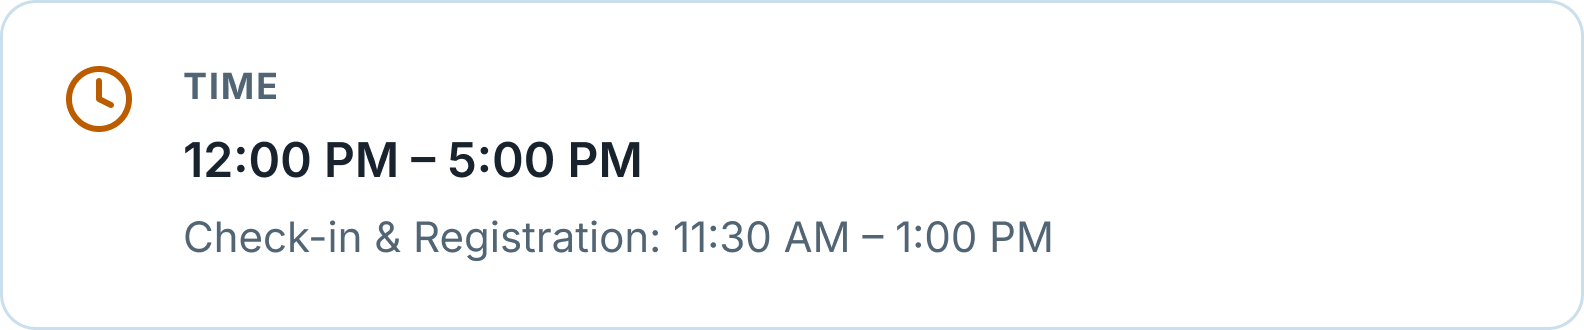
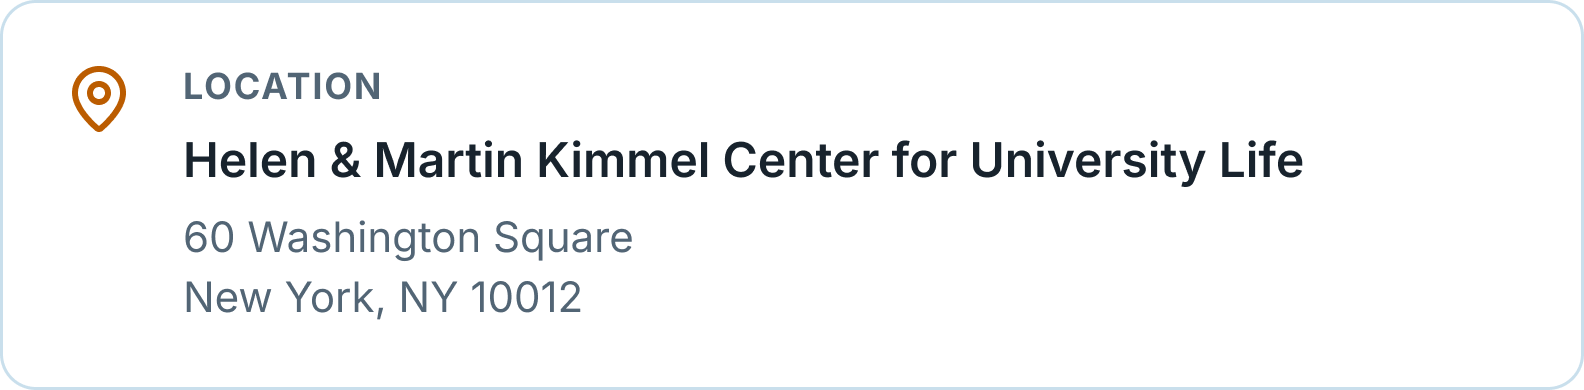
E V E N T D E T A I L S
Everything You Need to Know
Reserve Your Place
EARLY BIRD
Early Bird Registration
Academic Affiliate
Non – Academic Affiliate
$40
$50
REGISTRATION OPENS SEPTEMBER 15
REGULAR
Regular Registration
Academic Affiliate
Non – Academic Affiliate
$50
$65
REGISTRATION OPENS AFTER OCTOBER 1st
R E G I S T R A T I O N
E V E N T P R O G R A M
A Focused Afternoon of Insight and Connection
Join industry leaders, experienced alumni, and future quantitative finance professionals for keynote discussions and focused sessions.
12:00 PM - 12:45 PM
Keynote Leif B. Anderson - Global Co-Head of The Quantitative Strategies & Data Group, Bank of America
Quants, Strats, and AI: Perspectives from the sell-side
12:45 PM - 1:45 PM
Panel One Year Later - Conversation with Alumni
A panel of recent graduates from different Masters programs in Quant Finance and Financial Engineering speak about the first year out of graduate school. Panelists will discuss the job search process, how AI is changing the process, and what students should be thinking about for their first post graduate job.
Dhruv Shah - Execution Risk, Millennium
Xiaoxi (Susie) Xu - Quantitative Researcher, Bank of America
Hamza Zbiri - Quantitative Developer, OTCFin
1:45 PM - 2:30 PM
Panel Quantitative Risk in Practice - Lessons for the Next Generation
A panel of veteran quant risk practitioners joins our master's students for a candid discussion on model risk, market stress, and the judgment that numbers alone can't provide.
Romain Benvunto - Head of Equity Structuring Americas, Natixis Corporate and Investment Banking
2:30 PM - 3:15 PM
Panel AI In Finance: — Hype, Reality, and What Comes Next
A panel of practitioners building and deploying machine learning across trading, risk, and portfolio management joins our master's students to separate genuine edge from marketing gloss, and to discuss where AI is reshaping the discipline and where the fundamentals still hold.
3:15 PM - 4:00 PM
Panel Inside Quant Research — From Market-Making to the Rates Desk
A panel of quant researchers spanning market-making, options and rates modeling, and applied research joins our master's students to discuss how research ideas actually make it into production, and what separates a strategy that works on paper from one that survives contact with the market.
Michael Catalano-Johnson - Head of Quantitative Research, Susquehanna International Group (SIG)
Paul Guillaume Fournie - Options Rate Quant, BNP Paribas
Jay Yao - Quant Modeler, Blackrock
4:00 PM - 5:00 PM
Networking
C O N T A C T U S
Have Questions
About Industry Day?
Our team is here to help with registration, event details, academic affiliate information, and general inquiries.